TDSR and MSR explained: how much home loan can you get?
Banks do not lend based on the price alone. They test whether your income can carry the loan. Two rules matter.
TDSR: Total Debt Servicing Ratio
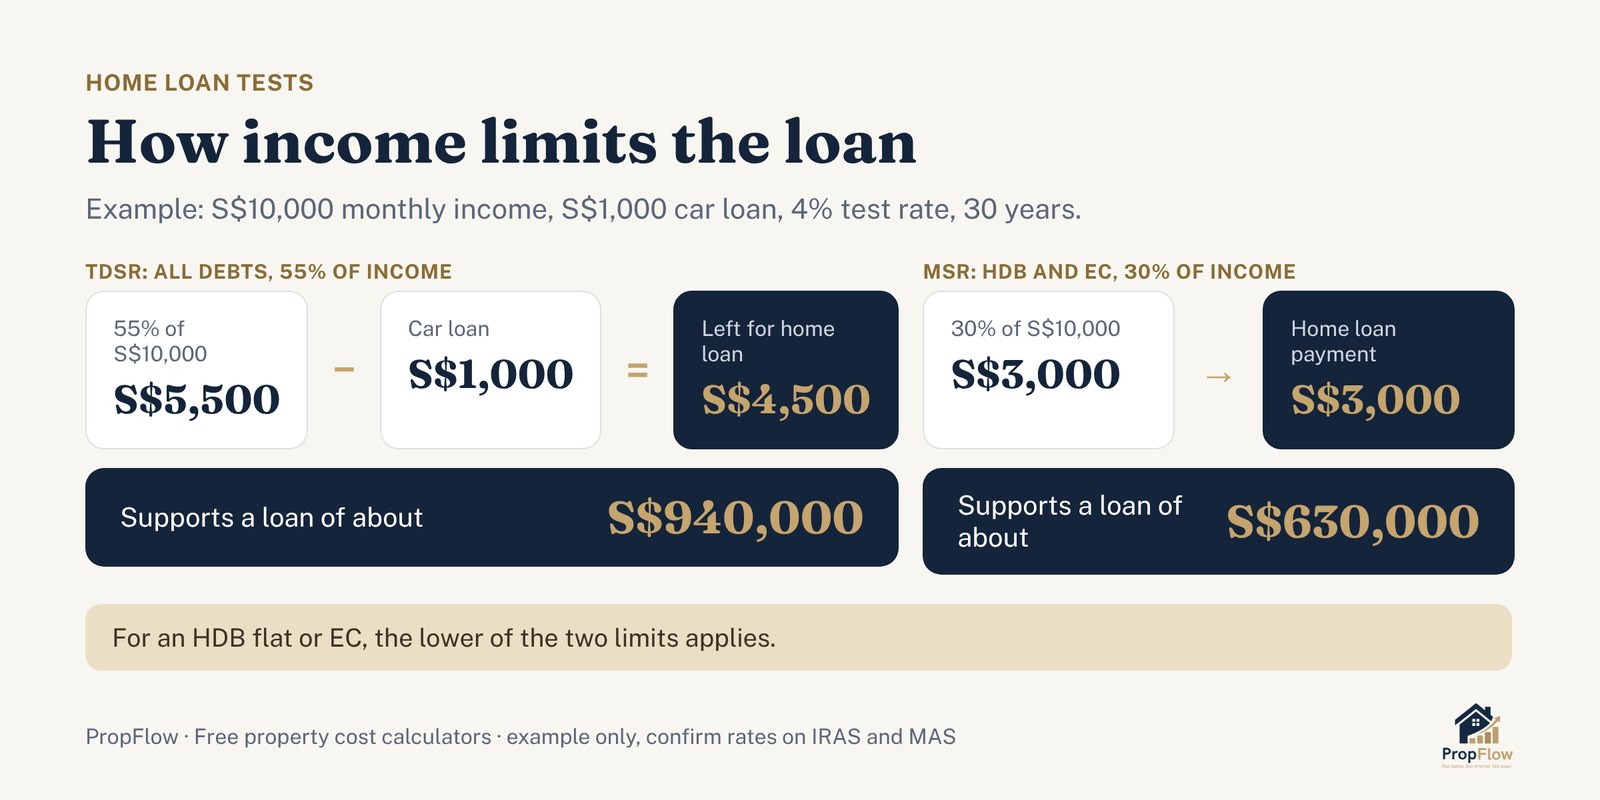
All your monthly debt payments, including the new home loan, cannot exceed 55% of your gross monthly income. Car loans, personal loans and credit card balances count. The bank tests the home loan at a higher assumed interest rate (a floor of 4%), not today's lower rate.
MSR: Mortgage Servicing Ratio
For HDB flats and executive condominiums bought with a bank loan, the home loan payment alone cannot exceed 30% of gross monthly income.
Worked example
Monthly income S$10,000 and a car loan of S$1,000 a month. TDSR allows S$5,500 in total debt, so S$4,500 is left for the home loan. At the 4% test rate over 30 years, that supports a loan of about S$940,000. For an HDB flat, MSR allows S$3,000 a month, or about S$630,000 at the same assumptions. The lower figure applies.
What else changes the answer
Variable income such as bonuses is usually counted at only 70%. Loan tenure, your age, existing loans and the loan-to-value limit also matter. See how much cash you need.
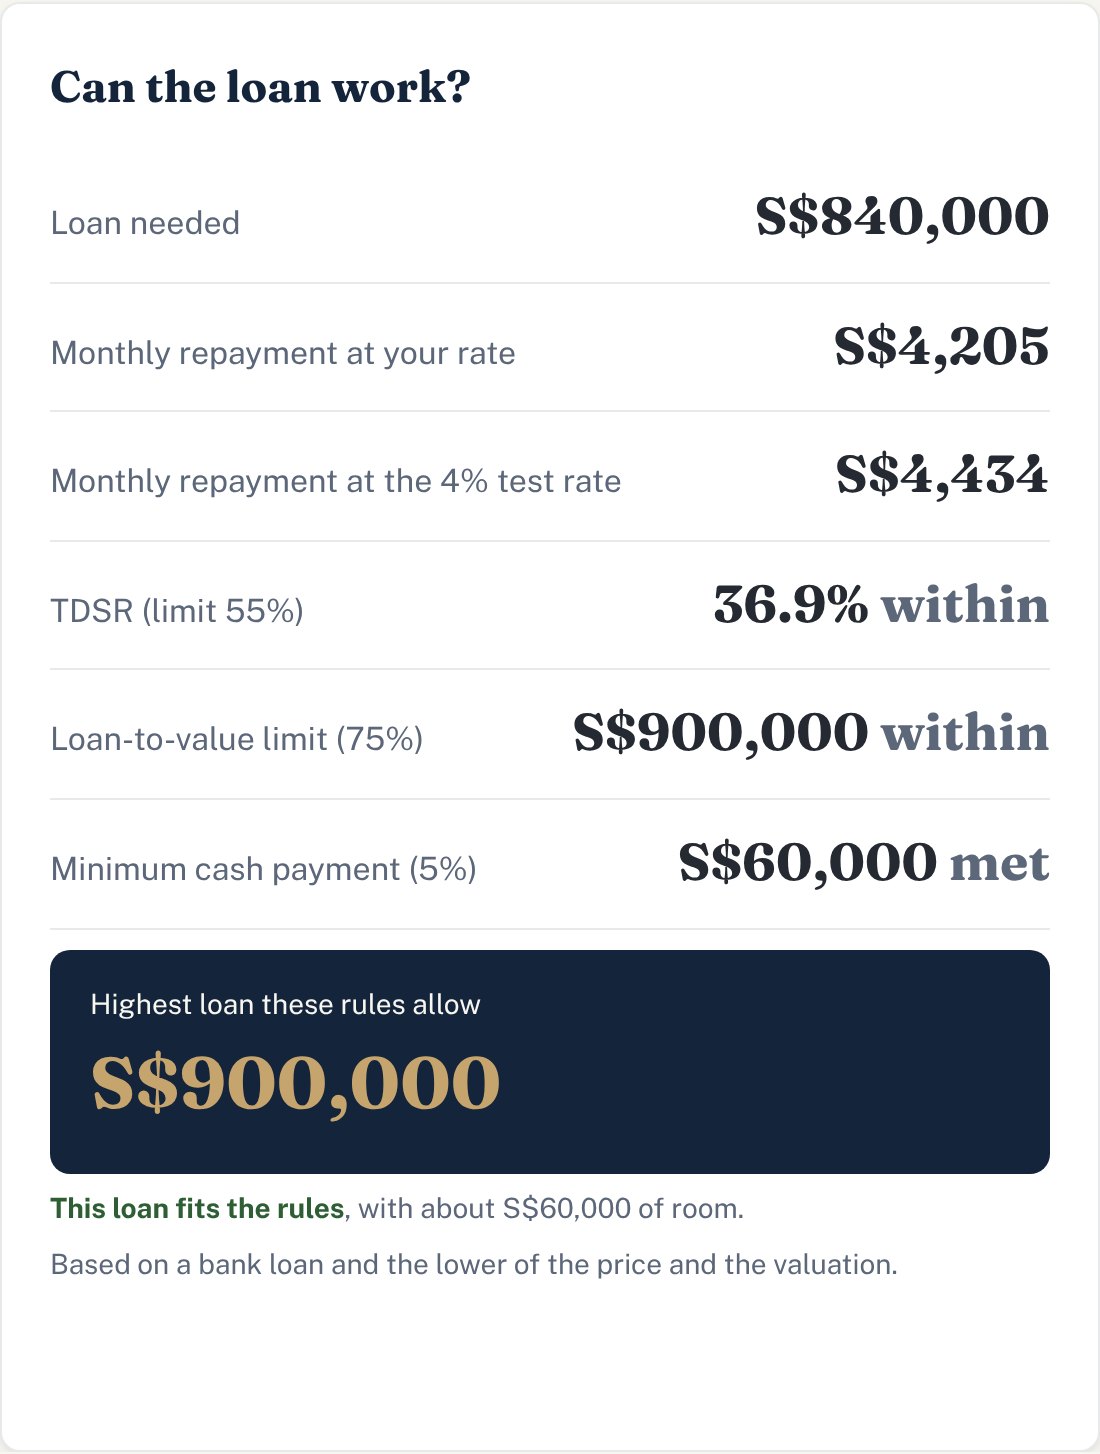
Enter your own income and debts in the free PropFlow calculator to see the loan you may qualify for and what is limiting it.
Try it now: PropFlow or open the free calculator.
This is a rough guide. Banks apply their own policies, so ask for an in-principle approval before you make an offer. General information only, not financial advice.