How much cash do you need to buy a property in Singapore?
The price on the listing is only part of the money you need on completion. Here is what to plan for.
1. Down payment
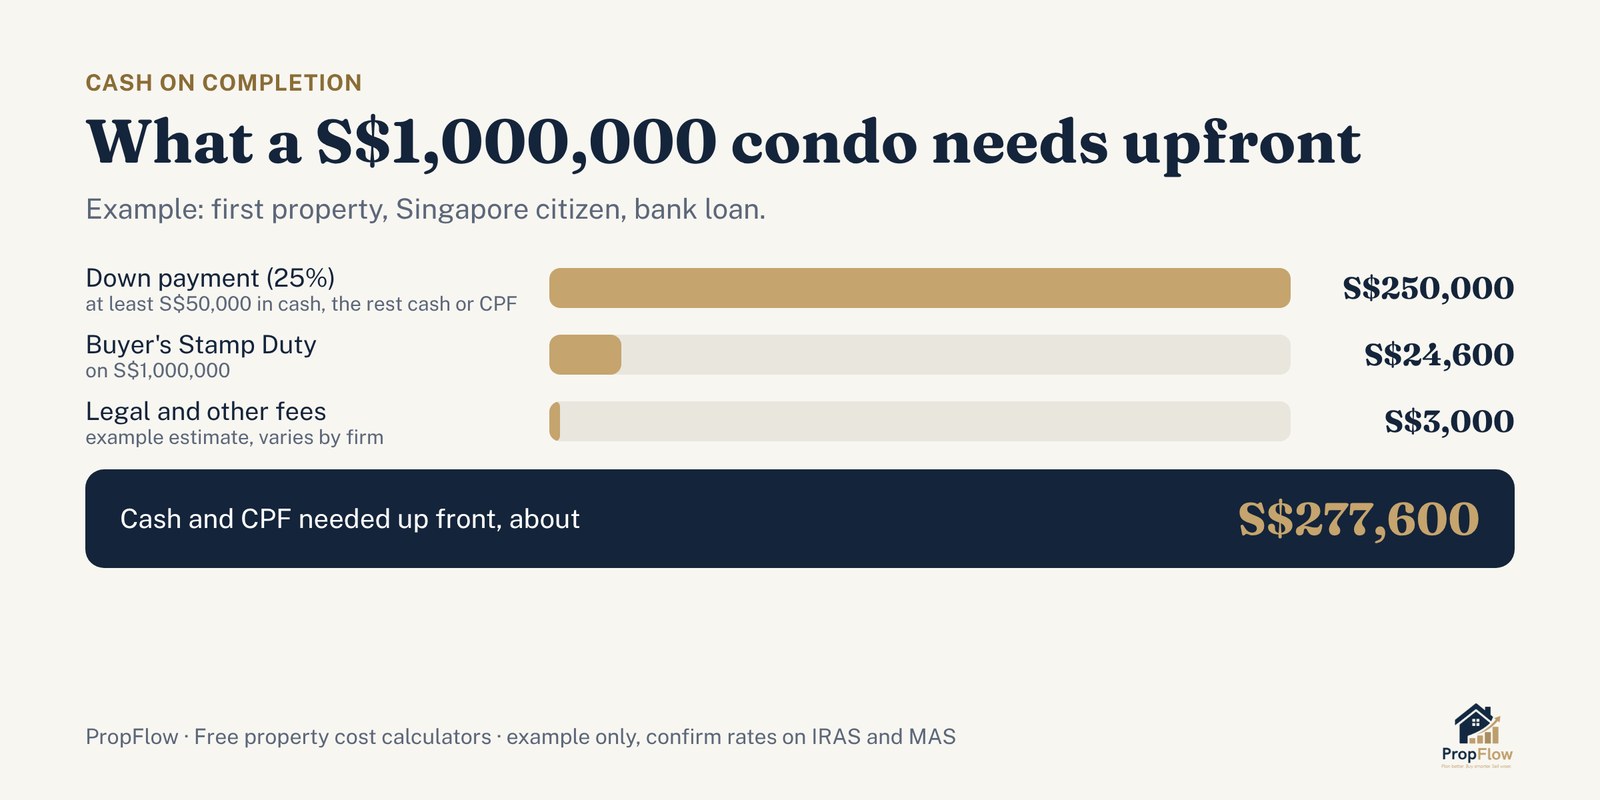
For a bank loan on a first housing loan, the limit is normally 75% of the price or valuation, whichever is lower. The remaining 25% is the down payment. At least 5% of the price must be paid in cash, and the rest can come from CPF. Loan limits are lower if you already have housing loans, or if the loan is long or runs past age 65.
2. Buyer's Stamp Duty (BSD)
Paid on every purchase, on a sliding scale. On a S$1,000,000 home it comes to S$24,600.
3. Additional Buyer's Stamp Duty (ABSD)
Depends on your residency and how many properties you own. It can be a large extra cost, so check it before you commit. Read our guide to BSD and ABSD.
4. Legal, valuation and other fees
Budget a few thousand dollars for conveyancing, valuation and fire insurance. Amounts vary by firm and property.
Worked example
A S$1,000,000 condo, first property, Singapore citizen: down payment of S$250,000 (at least S$50,000 in cash, the rest cash or CPF), plus BSD of S$24,600, plus fees. You also need to pass the bank's income test. See TDSR and MSR explained.
Try your own numbers on the free PropFlow calculator. It shows duties, loan limit and the cash you need.
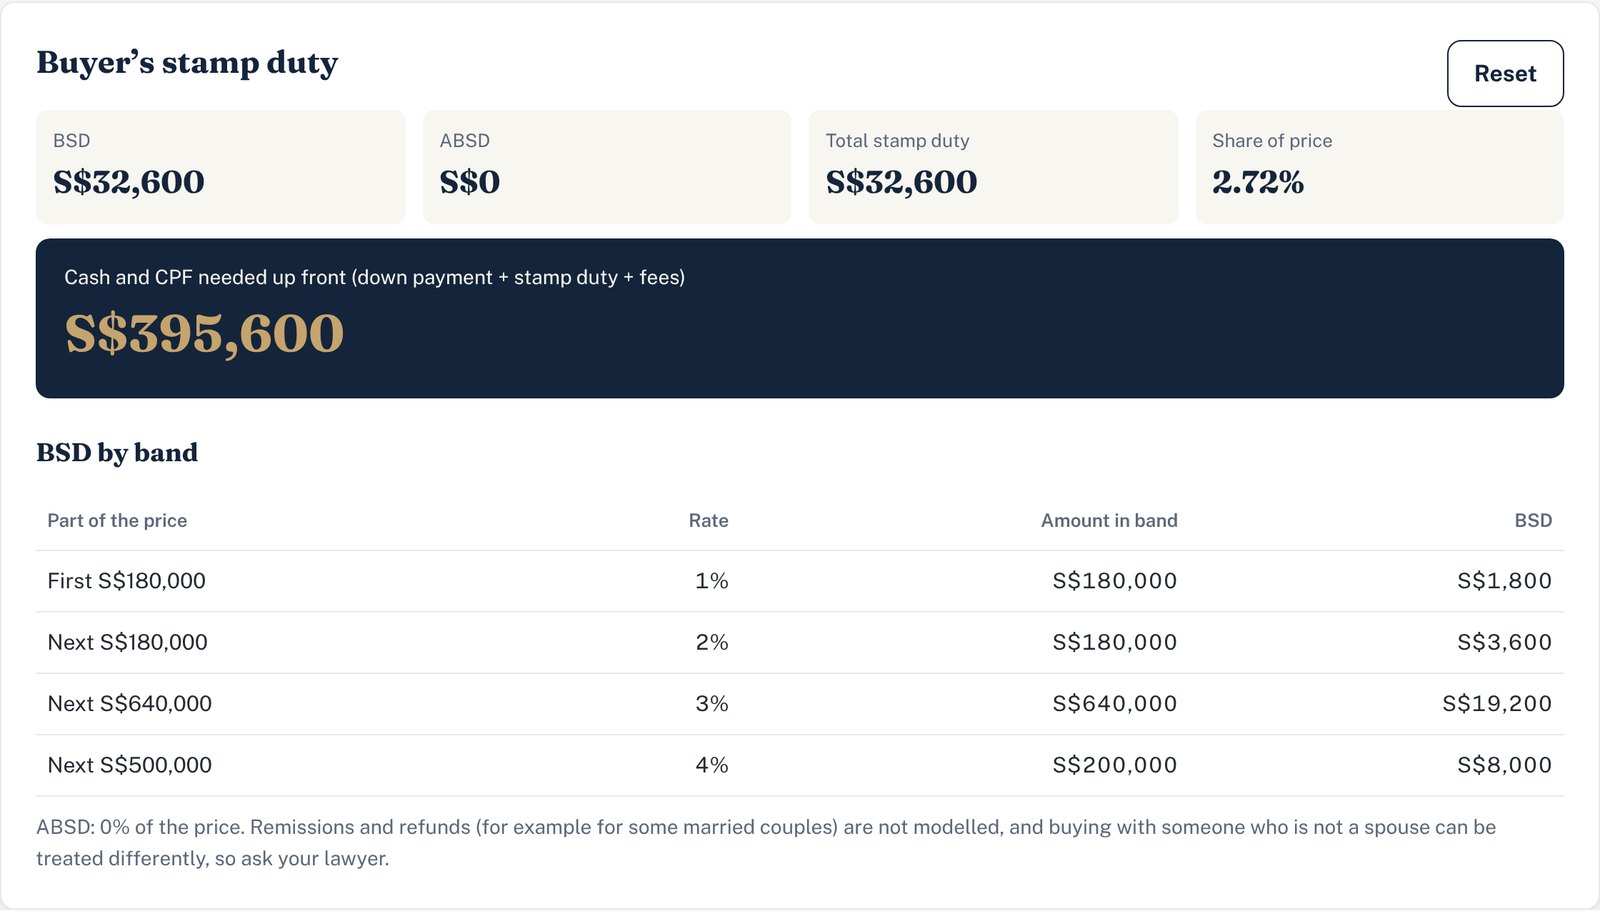
Try it now: PropFlow or open the free calculator.
General information only, not financial or legal advice. Rates change, so confirm on the IRAS and MAS websites and with your bank.